What Medicare Advantage extra benefits can include
Medicare Advantage (Part C) is a private-plan alternative for receiving your Medicare health coverage. Most plans include Part D prescription drug coverage, and plans may offer extras such as dental, vision, hearing or fitness benefits. The extras, eligibility rules and costs depend on the specific plan and service area. This guide was checked October 13, 2026; always use the documents for the plan year you are comparing.
Benefits you may see when comparing plans include:
- Prescription drug coverage: Included in most Medicare Advantage plans. Check the covered-drug list, pharmacies, deductible and cost sharing. Part D is a separate Medicare benefit, rather than a universal supplemental perk.
- Dental: Some plans cover preventive or other dental services, subject to their covered procedures, providers and dollar limits.
- Vision: A plan may cover routine eye exams or an allowance for eyeglasses or contacts. Check the amount, frequency and participating providers.
- Hearing: Some plans offer hearing-related benefits. Check device coverage, vendors and your share of the cost.
- Fitness: A participating plan may offer gym access or a home fitness program. Ask which facilities or services are included.
- Over-the-counter items: An allowance may pay for eligible products. Check approved items, participating retailers, spending periods and expiration rules.
- Transportation: Some plans offer eligible trips, with limits on destinations, distance, number of trips or advance booking.
- Telehealth: Plans may offer additional virtual services. Original Medicare also covers eligible telehealth services; it is not exclusive to Medicare Advantage.
- Meals: A plan may offer meals for certain recovery or health situations. Check eligibility and the number of meals covered.
- Caregiver support: Some plans offer resources or assistance for eligible members and their caregivers.
Medicare pays private plans to provide covered care. Extra benefits are part of a plan’s benefit design and funding arrangements; they do not guarantee lower total costs or access to every provider. Consider network rules, prior approval, cost sharing and the annual medical spending limit alongside the extras.
Use the plan’s Evidence of Coverage and Summary of Benefits to confirm what is included. An advertisement or general article cannot establish your personal eligibility or the amount a particular plan will pay.
The sections below explain common benefits, restrictions and practical questions to ask before enrolling.
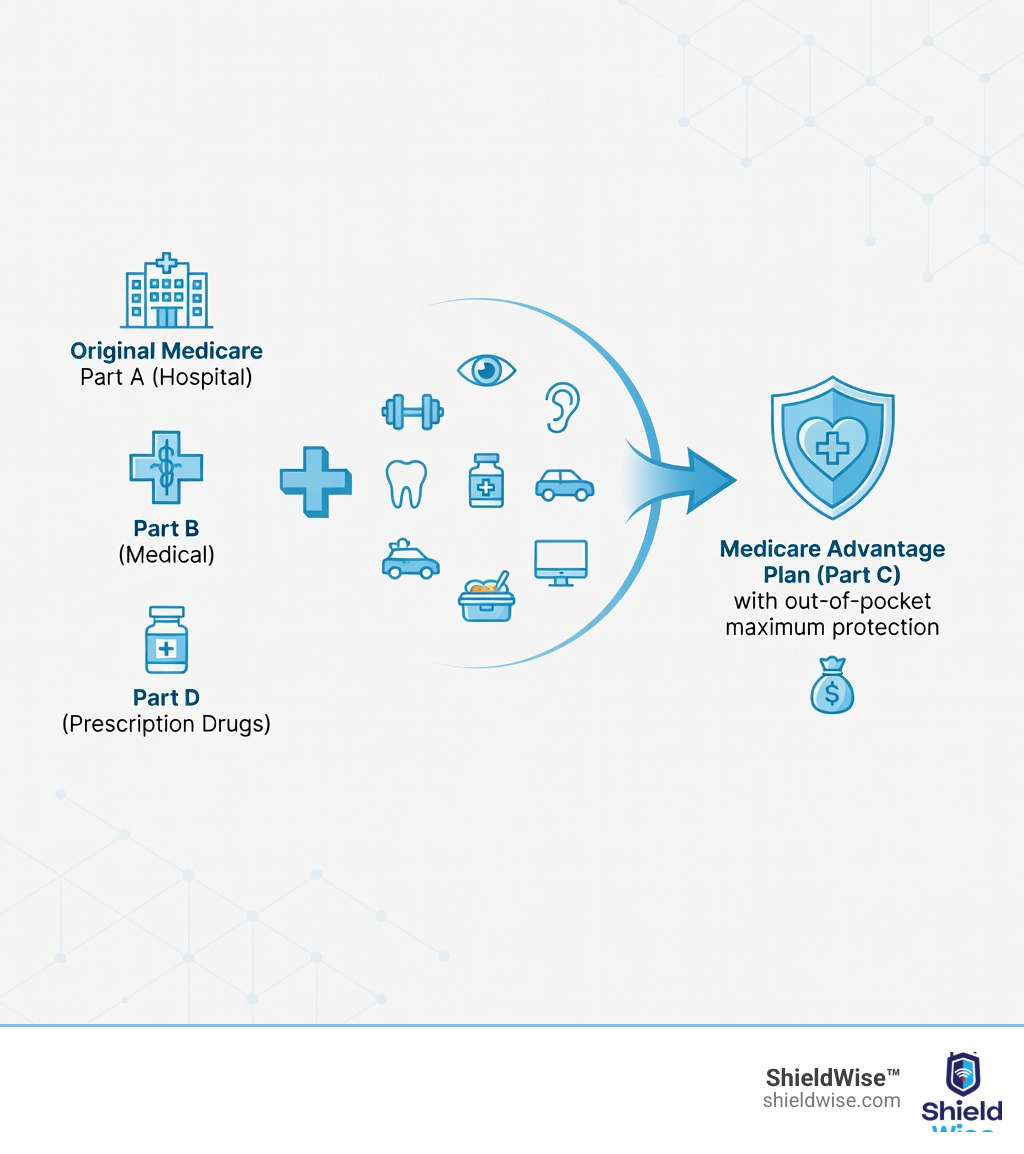
Medicare Advantage Extra Benefits Explained: How They Differ from Original Medicare
Original Medicare includes Part A and Part B. It generally does not cover routine eyeglass exams, hearing aids or most dental care, although exceptions can apply to specific medical services. Medicare explains those distinctions in its coverage guidance. An Advantage plan may offer additional coverage, with its own limits.
Medicare Advantage plans are offered by Medicare-approved private insurers. They provide your Part A and Part B benefits, but some services, including hospice care and certain clinical-trial costs, continue to be paid through Original Medicare. Coverage rules and cost sharing can differ. Use Medicare’s Understanding Medicare Advantage Plans guide for the details.
| Feature | Original Medicare | Medicare Advantage |
|---|---|---|
| Providers | Generally providers who accept Medicare, throughout the U.S. | Network and out-of-network rules depend on the plan type and service |
| Prescription drugs | Most outpatient prescription coverage requires separate Part D or other qualifying drug coverage; some drugs are covered under Part A or B | Most plans include Part D; confirm the covered drugs and pharmacies |
| Annual medical spending limit | No built-in Part A/B annual cap; supplemental coverage may help with costs | A plan-specific limit for covered Part A/B services; premiums, Part D and other expenses can be separate |
| Routine extras | Routine dental, eyewear and hearing aids generally are not covered; specific medical exceptions can apply | May include supplemental benefits, with plan-specific eligibility, allowances and member costs |
Medicare Advantage has an annual limit on what you pay for covered Part A and Part B services. That is not a ceiling on every expense: premiums, Part D drug spending and services outside the medical benefit can be separate. Plans can have different limits for in-network and combined in/out-of-network care. Original Medicare itself does not have an annual Part A/B spending cap, although supplemental coverage can help with costs. Check Medicare’s cost guidance and the specific plan documents.
How bundled coverage works
A Medicare Advantage card is generally used for services covered by that plan, and most plans include drug coverage. Keep your original Medicare card: some services still use Original Medicare, and you will need it if you return to that coverage. A single plan card does not guarantee that every extra benefit uses the same provider or vendor.
Ask how the plan coordinates care and whether you need a primary care doctor or specialist referral. A bundled plan does not necessarily put all medical records in one system or guarantee better outcomes. Our Medicare Advantage guide gives more background on the plan types.
Common and Innovative Supplemental Benefits
Routine dental, vision and hearing benefits are common features to compare, but their scope is not standardized across plans. Original Medicare may cover some medically necessary services in these areas, so distinguish routine extras from covered medical care.
- Prescription drugs: Compare your actual medicines, doses and pharmacies. An HMO or PPO generally must include drug coverage if you want Part D through that plan; you generally cannot add a separate drug plan to an HMO or PPO without drug coverage. Other plan types have different rules. See Medicare’s HMO guidance and our Part D explanation.
- Dental care: Compare covered procedures, annual allowances, visit limits, participating dentists and any copayments. A plan that covers cleanings does not necessarily cover crowns, dentures or implants.
- Vision: Ask whether routine exams and eyewear are included, how often you can use the benefit and whether an allowance covers the full price of your chosen glasses. There is no single nationwide allowance for every plan.
- Hearing: Compare the covered hearing aids, fitting services, replacement rules and vendors. An advertised hearing benefit can still involve substantial member costs.
For fitness benefits, check the actual participating facilities, online options and any equipment rules before joining. A gym near your home may not participate in a particular plan’s program, and the benefit is not available in every plan.
An OTC or benefit card is a restricted way to use a plan allowance, rather than unrestricted cash. Ask which products and retailers qualify, whether you must meet additional eligibility criteria, when the balance resets or expires, and whether you must pay anything beyond the allowance. Do not assume the same card covers groceries, utilities or every health-related purchase.
Other supplemental benefits to check
Some plans offer help beyond routine office visits. Availability can change by plan and year, and individual benefits can require a qualifying health condition, discharge event or assessment. Treat the following as examples to investigate, rather than a list every member receives:
- Transportation: Confirm eligible destinations, trip limits, scheduling requirements and whether an escort or wheelchair-accessible vehicle is included.
- Meal delivery: Ask which discharge or health conditions qualify, how long the benefit lasts and whether dietary needs can be accommodated.
- Caregiver support: Check whether the benefit is information, coaching, respite assistance or another defined service, and how it is accessed.
- Home-related assistance: A plan may offer certain safety or support services for eligible members. Obtain the written rules; this is not a general home-renovation allowance.
Confirm these benefits in the current plan documents and call member services when eligibility is unclear. The existence of a benefit in one insurer’s marketing material does not establish coverage in another plan or county.
Benefits for Chronic Conditions
A Special Needs Plan (SNP) serves an eligible group, such as people with specified chronic conditions, people with both Medicare and Medicaid, or people who need an institutional level of care. Its availability and enrollment requirements matter. Special Supplemental Benefits for the Chronically Ill (SSBCI) are a separate benefit category with additional eligibility rules; a diagnosis, SNP membership or card advertisement does not automatically qualify you for every allowance.
Check your benefits directly rather than wait for a reminder about unused allowances. CMS delayed enforcement of the earlier mid-year-notice requirement for 2026 and finalized its rescission in the April 2026 rule. Ask member services which benefits you are eligible for, how to use them and when any allowance expires.
The Fine Print: Affordability and Limitations of Extra Benefits
Extra benefits are only one part of the comparison. Start with your medical care, prescription access and likely annual costs, then evaluate whether the extras are useful to you.
Network rules depend on the plan type. An HMO generally requires network providers, with exceptions such as emergency care, out-of-area urgent care and temporary out-of-area dialysis. A PPO generally allows covered out-of-network care at higher cost. Confirm that the provider accepts the specific plan and service; accepting Medicare alone is not enough.
Other limitations include:
- Prior authorization: Some services need approval before the plan will cover them. Ask how approval and appeals work, particularly for treatment you already receive.
- Benefit caps and cost sharing: A dental or eyewear allowance can have its own dollar limit, excluded procedures or member costs. Ask for an estimate for the actual service instead of assuming the allowance pays the whole bill.
- Annual changes: Private-plan benefits and costs can change from one year to the next. Provider participation can also change. Recheck coverage each year and when a provider notifies you of a change.
Review your Annual Notice of Change, which arrives in the fall and describes changes effective in January. Medicare says to expect it in September. Contact the plan if it does not arrive, and read the new Evidence of Coverage before deciding to stay.
How extra benefits are funded
A $0 additional plan premium does not mean all care or extras are free. You still need Part B and must keep paying its premium, subject to any assistance or plan premium reduction. A plan can also have copayments, coinsurance, deductibles and limits on its extras.
Medicare payments, the plan’s bid and rebate arrangements, premiums and benefit design help determine the coverage a private insurer offers. Networks and purchasing arrangements also influence costs. Compare the actual plan terms rather than assume that a preventive perk guarantees savings or a better health outcome.
How to Evaluate and Compare Plans
Plans vary by service area. Use your own ZIP code and county, and select the correct coverage year when comparing. An option available in one part of Illinois may not be available where you live.
Start with Medicare Plan Finder. Enter your medicines and pharmacies, then review plan costs, benefits and quality information. Star ratings are one comparison tool; a high rating does not prove that your doctor participates or that the plan covers your particular needs.
Compare expected annual expenses and a high-use scenario, including premiums, medical cost sharing, prescriptions and services not covered by the plan. The medical maximum alone is not your total annual budget. Our out-of-pocket costs guide explains the different types of charges.
Questions to ask before enrolling
Use these questions to compare the actual plan documents and confirm the answers with the plan and your providers:
- Are my providers available? Check the plan directory and ask both the provider and plan about the specific plan, location and service. Also ask about referrals, prior authorization and care while traveling.
- Are my medicines covered? Check the formulary, drug tier, pharmacy network and restrictions such as prior authorization or step therapy. Use your actual dose and pharmacy to estimate costs.
- Which extras can I use? Confirm eligibility, participating vendors, allowance amounts, frequency, expiration rules and any costs above the benefit. Choose based on realistic needs rather than the number of advertised perks.
- What does the medical maximum cover? Check the Part A/B limit and any separate in-network/out-of-network limits. Add premiums, Part D drug costs, excluded care and extra-benefit costs separately when estimating your budget.
Frequently Asked Questions about Medicare Advantage Extras
How do Medicare Advantage plans afford to offer extra benefits?
Medicare pays plans to provide covered care, and plan bids and rebate arrangements can fund supplemental benefits or reduce certain premiums and cost sharing. That funding does not make every extra unlimited or available to every member. Read the benefit rules for the specific plan.
Can I get extra benefits if I have a pre-existing condition?
A pre-existing condition generally does not prevent enrollment in a Medicare Advantage plan when you otherwise meet its enrollment requirements. People with End-Stage Renal Disease can also join. However, receiving a particular extra benefit can require separate eligibility checks, and an SNP restricts enrollment to its qualifying group. Confirm the plan’s service area, your Part A/B coverage and your enrollment period using Medicare’s enrollment guidance.
Do all Medicare Advantage plans offer the same extra benefits?
No. Coverage, limits and eligibility differ across insurers, counties, plan years and individual plans. Some plans may help reduce part of the Part B premium; others emphasize different benefits. Compare the exact plan identification and year, and do not assume that a similarly named plan has identical coverage.
Your next step
Start with the providers, medicines and care you need. Extra benefits can be useful, but they should be weighed alongside access rules and total costs. Keep copies of the plan documents and any written answers you rely on.
If you are turning 65 or considering a change, confirm which enrollment period applies. Do not cancel existing coverage before confirming eligibility and the new coverage start date.
Compare current local options through Medicare Plan Finder and contact the plan with benefit questions. For free independent counseling, Medicare’s enrollment page links to your State Health Insurance Assistance Program. These resources can help you check the trade-offs before you choose.